

A home warranty can help manage repair costs after a heating or cooling system breaks down. Coverage often includes central air systems, furnaces, heat pumps, thermostats, and selected internal parts. However, every agreement has limits, exclusions, service charges, and replacement caps. Owners who review those details before a failure can make better budget decisions. Knowing how claims work also helps households distinguish warranty protection from homeowners insurance and manufacturer coverage.
The Short Answer
Coverage decisions often begin with one practical question: does home warranty cover HVAC? The answer usually depends on the contract, the system’s condition, and the cause of the failure. Most plans address breakdowns caused by ordinary use, while exclusions can apply to neglected upkeep, faulty installation, or damage from outside events. Reading those terms before enrollment helps owners estimate possible costs and avoid surprises.
How HVAC Warranty Coverage Works
A covered system usually follows a simple claim process. The homeowner contacts the provider and pays a service fee. Next, an assigned technician inspects the equipment and identifies the failed component. If the agreement applies, the company authorizes a repair or offers a contribution toward replacement. Payment limits, diagnosis findings, and contract language determine the final amount.
Parts Commonly Included
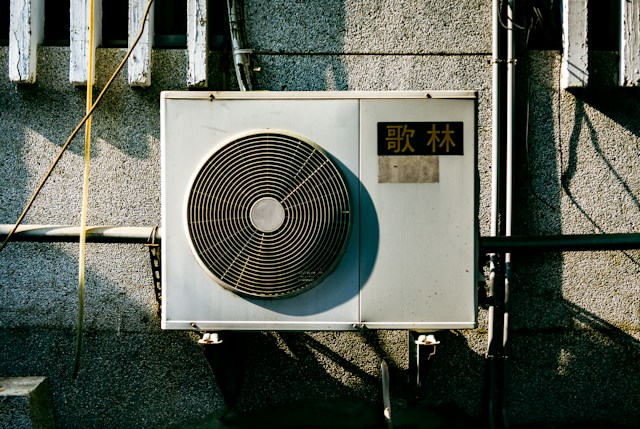
Many agreements cover central air conditioners, furnaces, heat pumps, thermostats, compressors, motors, and air handlers. Some plans also include refrigerant, ductwork, mini-split equipment, or geothermal units. Coverage differs by provider and package. Window units may fall outside standard protection. Owners should confirm each component before choosing a plan, especially in homes with multiple systems.
Service Fees and Coverage Caps
A service fee applies each time a technician visits for a covered issue. That charge remains separate from annual or monthly plan costs. Contracts may also set maximum payments for certain parts, labor, refrigerant, or complete equipment replacement. A low membership price may look attractive, but a small benefit limit could lead to a larger final bill.
Common Exclusions
Warranty providers often exclude preexisting defects, improper installation, code violations, cosmetic damage, and failures linked to poor care. Storm damage, flooding, fire, and other sudden hazards generally belong under homeowners insurance. Manufacturer guarantees may also cover newer equipment. Checking these boundaries prevents owners from submitting a claim under the wrong form of protection.
Why Maintenance Records Matter
Regular filter changes, professional inspections, and clear repair records can support a claim. Documentation gives the technician evidence that the system received reasonable care. Some agreements require maintenance before approving certain repairs. Missing records do not always cause an automatic denial, but they can complicate a review. Keeping invoices and service notes creates a useful paper trail.
Can a Warranty Pay for Replacement?
A provider may authorize replacement if repair is impractical or the equipment cannot operate safely. The payment often depends on the contract’s cap, the item’s listed value, and available parts. Owners may still pay for permits, upgrades, code changes, disposal, or differences between a basic replacement and a preferred model. Replacement assistance rarely means unlimited funding.
Warranty Protection Versus Insurance
A home warranty addresses mechanical failure from regular use. Homeowners insurance generally covers sudden damage from covered hazards, such as lightning, fire, or wind. These products serve different purposes and may work together. For example, a storm-damaged outdoor unit may require an insurance claim, while an aging compressor may fit warranty coverage.
Is HVAC Coverage Worthwhile?
Value depends on equipment age, repair history, household savings, and regional climate. Older systems may fail more often, while newer units may remain under a manufacturer guarantee. A plan can provide predictable service fees, but exclusions and caps deserve careful review. Owners should compare expected premiums, likely repairs, and replacement exposure before enrolling.
Questions Owners Should Ask
Before selecting a contract, homeowners should ask which heating and cooling systems qualify, whether permits are included, and how refrigerant costs are handled. Other useful questions involve service fees, contractor choice, response times, replacement limits, maintenance rules, and cancellation terms. Written answers provide stronger protection than assumptions made during a sales conversation.
Conclusion
A home warranty can cover many HVAC repairs, but approval depends on the service agreement and the cause of failure. Normal wear may qualify, while neglected maintenance, installation problems, and outside damage often do not. Owners can reduce confusion by reviewing exclusions, recording upkeep, and checking payment limits. Careful comparison helps households choose protection that matches equipment age, local conditions, and available savings.
Email your news TIPS to Editor@Kahawatungu.com — this is our only official communication channel
