

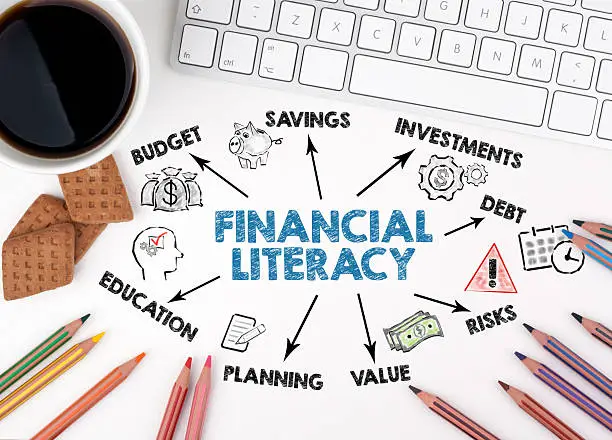
Financial literacy is the ability to understand and manage money effectively. Learning how to improve financial literacy can help you make better decisions about saving, spending, borrowing, investing and planning for the future. Whether you are a student, employee, business owner or parent, developing strong financial knowledge can help you avoid unnecessary financial problems and make better use of your income.
-
Understand Your Income and Expenses
Start by understanding how much money you receive and how much you spend.
Keep track of your salary, business income, allowances or other sources of money. Then list your regular expenses, including food, housing, transport, bills and other payments.
Knowing where your money goes is an important foundation for making better financial decisions.
- Record all sources of income
- List regular expenses
- Track small purchases
- Review your spending regularly
-
Create a Realistic Budget
A budget helps you decide how your money should be used before you spend it.
Create a monthly budget based on your actual income and expenses. Allocate money to essential needs, savings, debt payments and other priorities.
Avoid creating a budget that is unrealistic because it may be difficult to maintain.
- Set spending limits
- Prioritize essential expenses
- Allocate money for savings
- Review the budget each month
-
Learn How to Save Money
Saving is an important part of financial literacy. Even small amounts can help you develop a regular saving habit.
Set a specific savings goal, such as building an emergency fund, paying school fees, purchasing equipment or preparing for a major expense.
Consider saving automatically when possible so that you do not have to rely entirely on willpower.
-
Build an Emergency Fund
An emergency fund provides money for unexpected expenses such as urgent repairs, temporary loss of income or other financial emergencies.
Start with an amount you can manage and gradually increase it over time.
Keep emergency savings separate from money intended for everyday spending.
- Set an emergency savings target
- Contribute regularly
- Keep the money accessible
- Use it for genuine emergencies
-
Understand Debt
Improving financial literacy also means learning how borrowing works.
Understand the interest rate, repayment period, fees and total cost before taking a loan. Compare different borrowing options rather than accepting the first offer you receive.
Avoid borrowing money simply to finance unnecessary spending.
- Understand loan terms
- Check interest rates
- Calculate repayment costs
- Pay debts on time
-
Learn About Interest
Interest can work either for or against you.
When you save or invest, interest can help your money grow. When you borrow, interest increases the amount you eventually repay.
Understanding simple and compound interest can help you evaluate savings accounts, loans and investments more effectively.
-
Learn the Basics of Investing
Once you understand budgeting, saving and debt management, learn the basics of investing.
Research concepts such as shares, bonds, funds, property and other investment options. Understand the potential return, risks, fees and time period associated with an investment before committing your money.
Do not invest in something simply because someone promises quick or guaranteed profits.
-
Set Financial Goals
Clear financial goals can make money management easier.
Your goals could include saving for education, buying a home, starting a business, building retirement savings or paying off debt.
Break larger goals into smaller targets and monitor your progress regularly.
- Set short-term goals
- Create long-term goals
- Give each goal a target amount
- Set a realistic deadline
-
Learn How to Compare Financial Products
Banks, lenders, insurance companies and investment providers offer different financial products.
Before choosing one, compare important factors such as fees, interest rates, benefits, penalties and terms.
Reading the details carefully can help you avoid choosing a product that does not suit your financial needs.
-
Learn About Taxes and Insurance
Taxes and insurance are important parts of personal financial planning.
Learn the basic taxes that may apply to your income or business activities. Also understand how insurance works and what different policies cover.
Knowing these concepts can help you plan for financial obligations and protect yourself against certain unexpected costs.
-
Use Reliable Financial Information
There is a lot of financial advice available online, but not all of it is accurate.
Use reliable educational resources, financial institutions, regulators and qualified professionals when researching important financial decisions.
Be particularly careful with social media posts promising quick wealth or guaranteed investment returns.
-
Teach Financial Literacy at Home
Financial literacy can be developed from an early age.
Parents and guardians can teach children about saving, budgeting, responsible spending and the difference between needs and wants.
Simple activities such as giving children a savings goal or involving them in basic household budgeting can help them develop useful money-management skills.
-
Review Your Financial Progress
Improving financial literacy is an ongoing process.
Set aside time each month to review your income, expenses, savings, debts and financial goals. Identify areas where you are doing well and areas that need improvement.
Regular reviews can help you make adjustments before small financial problems become larger ones.
Also Read: How to Improve Blood Circulation in Legs
Email your news TIPS to Editor@Kahawatungu.com — this is our only official communication channel
